
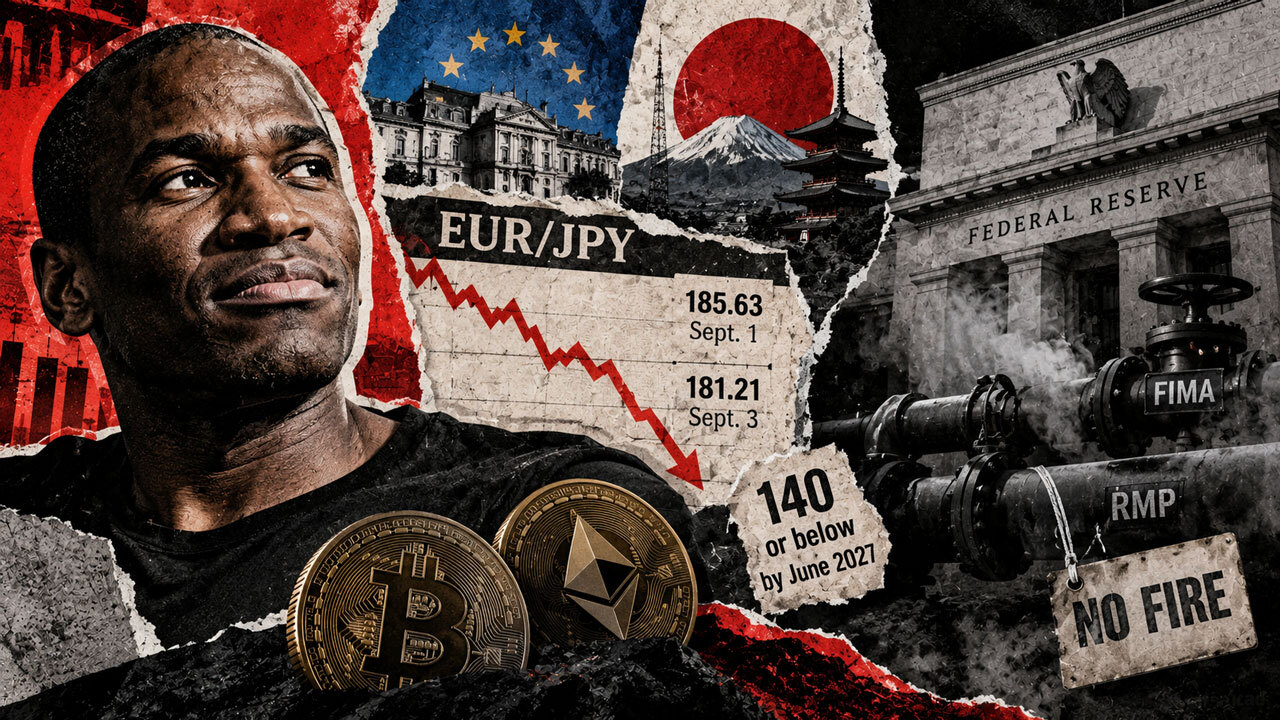
Arthur Hayes has a new market alarm for crypto traders: EUR/JPY. The pair has started to fall, yet the Federal Reserve channels that would turn currency stress into dollar liquidity remain dormant.
The European Central Bank’s reference rate fell from 185.63 yen per euro on Sept. 1 to 181.21 on Sept. 3, a 2.38% drop. Hayes says a fall to 140 or below by June 2027 would herald a much larger increase in dollar liquidity. The latest reading still sits 29.4% above that threshold.
That distance is crucial. The exchange rate is only the first link in a sequence that runs through French sovereign and bank funding, foreign central bank dollar borrowing at the Fed, and Fed purchases of Treasury securities. Current official data show vulnerability in France, but the rest of Hayes’s proposed chain has yet to activate.
The four-part EUR/JPY trade behind Hayes’s alarm
In his Sept. 2 essay “Atención,” Hayes argued that political and financial pressure in France would weaken the euro while Japanese capital repatriation strengthened the yen. A falling EUR/JPY would warn that French banks were nearing stress in sovereign and dollar repo markets.
Hayes then looks to two different Fed tools. The FIMA repo facility allows approved foreign monetary authorities to raise dollars temporarily against Treasuries. Reserve-management purchases, known as RMPs, add short-dated Treasury securities to the Fed’s portfolio to maintain an ample supply of bank reserves.
In his scenario, those channels expand the supply of dollars and ultimately support risk assets. Hayes kept a structural Bitcoin long and reiterated a $10,000 Ether target for the end of 2026. Those positions depend on the proposed mechanism and provide no confirmation that it has started.
The public scorecard makes the gap visible:
| Link in the thesis | Current reading | Signal that would strengthen the case |
|---|---|---|
| EUR/JPY breaks lower | 181.21 on Sept. 3, down from 185.63 on Sept. 1 | A sustained move toward 140 would validate the currency leg alone |
| French funding stress spreads | Higher sovereign yields and known repo vulnerabilities alongside a covered OAT auction and resilient aggregate bank-liquidity measures | Disorderly sovereign funding, weaker bank liquidity or funding data, and evidence of French banks retreating from repo markets |
| FIMA supplies emergency dollars | $0 outstanding in the latest H.4.1 release | A positive and rising foreign-official repo balance |
| Fed Treasury buying accelerates | No RMPs scheduled for the current monthly window | Renewed purchases tied to persistent reserve or market pressure rather than routine portfolio reinvestment |
| Crypto responds | Research supports broad sensitivity to Fed conditions, with no historical test of this exact chain | A concurrent liquidity expansion and crypto move that holds after accounting for other risk drivers |
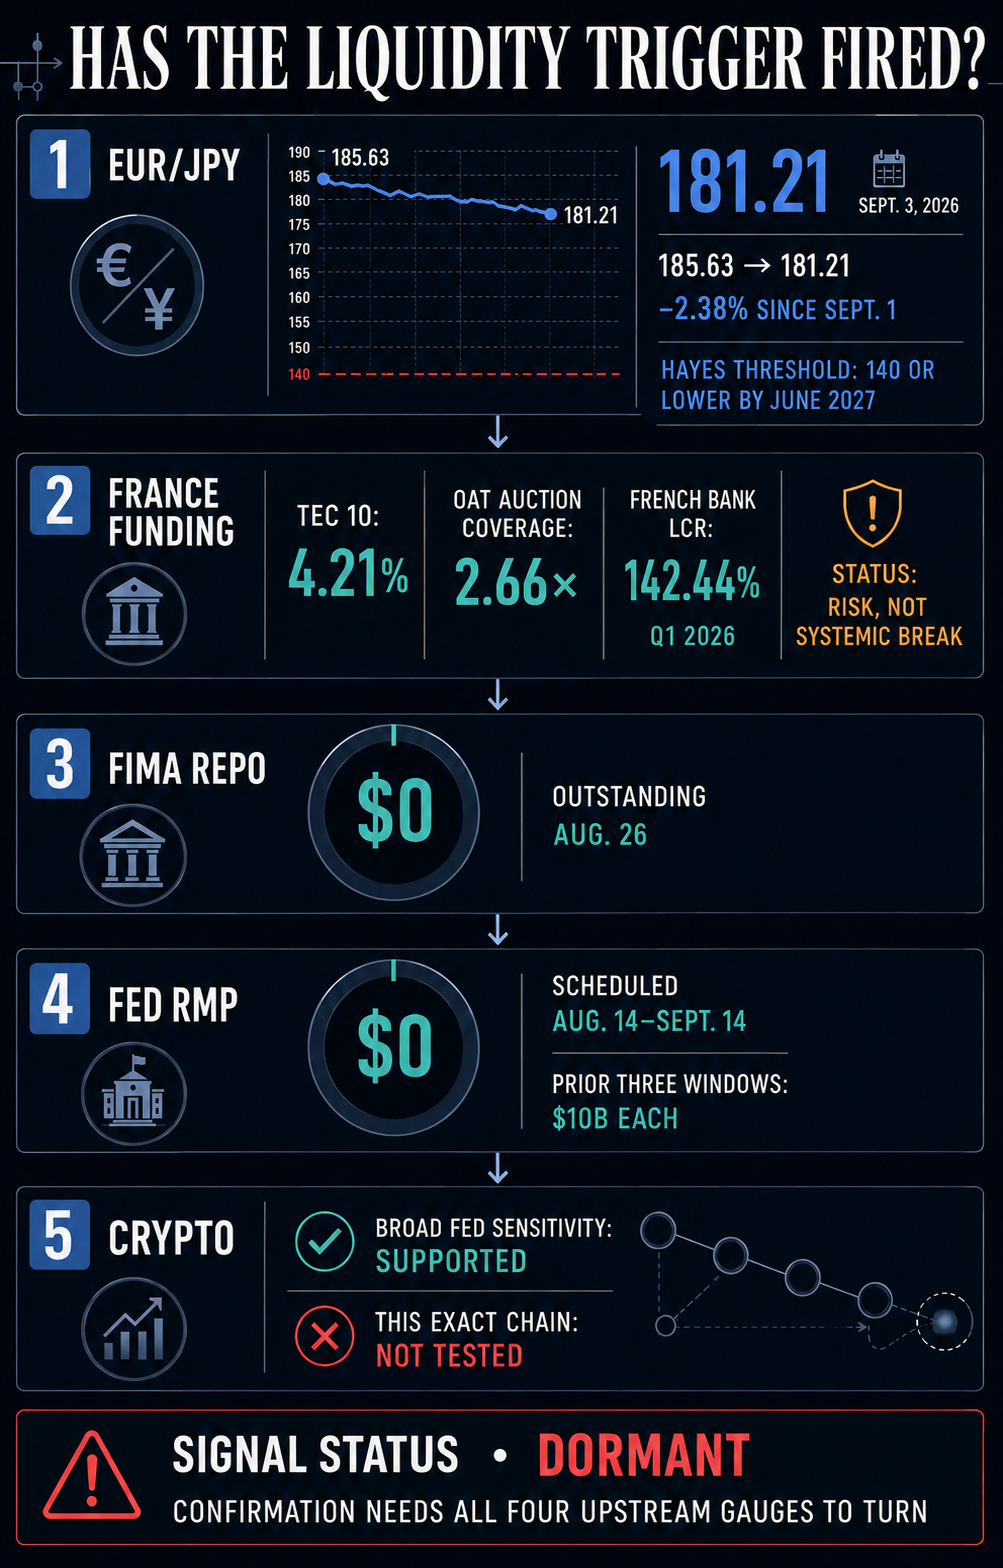
The table also shows why a lower currency pair cannot carry the argument by itself. Hayes’s forecast spans markets with separate participants, mandates and disclosure schedules. Confirmation requires those independent gauges to turn in sequence.
The Fed plumbing behind EUR/JPY remains dormant
The Fed describes FIMA repo as a backstop for approved foreign monetary authorities. They can temporarily obtain dollars against Treasuries instead of selling the securities into the market. The facility is generally priced above private repo when markets function normally, directing its use toward periods of unusual stress.
The latest H.4.1 balance sheet reported zero under “Repurchase agreements: Foreign official” for Aug. 26. The Fed’s accounting guidance identifies that line as outstanding FIMA repo. Central bank liquidity swaps were also small at $121 million.
A larger foreign-official figure in the same release measures the opposite transaction. Foreign-official and international-account reverse repurchase agreements averaged $361.883 billion for the week and stood at $355.456 billion on Wednesday. These reverse repos are a Fed liability used by foreign official institutions to invest cash. FIMA repo is an asset-side transaction in which the Fed supplies cash against Treasuries. Treating the reverse-repo balance as FIMA usage would invert the signal.
Hayes’s larger scenario assumes removal of the FIMA facility’s per-counterparty limit. The FOMC authorization in force as of Jan. 27 retained a $60 billion total outstanding limit per counterparty, although the relevant subcommittee can approve changes. Current policy therefore remains well short of the uncapped facility embedded in his forecast.
The RMP channel points in the same dormant direction. For the Aug. 14 to Sept. 14 window, the New York Fed scheduled about $17 billion of reinvestment purchases and zero reserve-management purchases. RMPs had already stepped down to $10 billion in each of the prior three monthly windows after running at $40 billion per month through mid-April.
Reinvestment replaces principal payments from maturing agency securities. RMPs increase Treasury holdings to maintain ample reserves. SOMA Manager Roberto Perli explained in March that the present program began after reserves entered the ample range in December 2025, with the initial $40 billion pace smoothing an expected April tax-season drain into the Treasury General Account.
Perli also placed RMPs outside the large-scale asset-purchase programs used to ease financial conditions during the global financial crisis and the pandemic. A renewed rise in RMPs would matter for Hayes’s framework only when accompanied by evidence that reserve or repo pressure was driving it. The current schedule shows deceleration to zero.
France supplies the live risk
French sovereign markets give Hayes’s thesis its strongest observable foundation. Agence France Trésor listed its 10-year benchmark yield at 4.21% on Sept. 3. The day’s long-dated OAT auction nevertheless attracted €35.879 billion of purchase orders for €13.497 billion served, producing about 2.66 times coverage.
The Banque de France’s June stability report had already identified the channel that could make future stress contagious. France’s 10-year yield reached 3.75% on June 12, while the OAT-Bund spread widened 8 basis points over the conflict period analyzed. The report warned that leveraged hedge-fund trades in OAT repo, often using very short maturities and potentially procyclical margin practices, could amplify a liquidity shock.
A separate ECB study of dollar repo funding gives the mechanism scale. Euro-area banks had about €1.6 trillion of dollar repo exposure in November 2024, with 85% maturing within one week and most government-bond collateral consisting of Treasuries. French bank branches were the most active euro-area branches in the U.S. repo market. The study established a structural channel; it reported no current French retreat from that market.
Aggregate bank data remain resilient. The ECB reported a 142.44% liquidity coverage ratio for French significant institutions in the first quarter of 2026. France’s bank supervisor said in July that liquidity and solvency were comfortable and that medium- and long-term funding programs were well advanced. Those lagged measures leave room for later strain, while offering no support for a systemwide funding break at the time measured.
France’s average TARGET balance was a liability of about €195.239 billion in June. TARGET records the net result of cross-border payments between national central banks, and the ECB publishes the series monthly with a lag. The balance can serve as a directional gauge of cross-border flows. On its own, it cannot establish a bank run or an imminent rupture in the euro.
Together, the French indicators describe a market carrying more risk rather than a system already in flight. Yields and repo structure justify close attention. Auction demand, capital and liquidity figures define the counterweight.
Crypto is the last link
Crypto’s sensitivity to Fed conditions gives the thesis an intuitive endpoint. International Monetary Fund research found that a common crypto factor explained 80% of price variation in its sample and that tighter U.S. monetary policy reduced that factor through the risk-taking channel.
That result links crypto broadly to monetary policy and global risk appetite. It falls short of establishing EUR/JPY as a reliable leading indicator for Bitcoin or Ether, and it does not test the path through French repo markets, FIMA and RMPs.
The proposed sequence also lacks enough direct history for a clean backtest. FIMA usage is currently zero, while the present RMP regime began only in December 2025. Repeated cases in which this exact sequence preceded crypto gains do not exist in the supplied evidence.
At the Sept. 3 research check, CryptoSlate’s Bitcoin market data showed BTC near $81,008, while its Ethereum market data showed Ether near $2,498. Those prices locate the market when Hayes published his forecast. Future gains would still need to be paired with the balance-sheet signals he named before they could count as evidence for his mechanism.
EUR/JPY remains the simplest gauge in Hayes’s framework, but its move only opens the test. A more persuasive signal would combine a sustained approach toward 140 with worsening French sovereign and bank-funding data, positive FIMA repo usage, and renewed RMPs tied to market pressure. Until those gauges turn together, Hayes’s smoke alarm remains at the monitoring stage.