
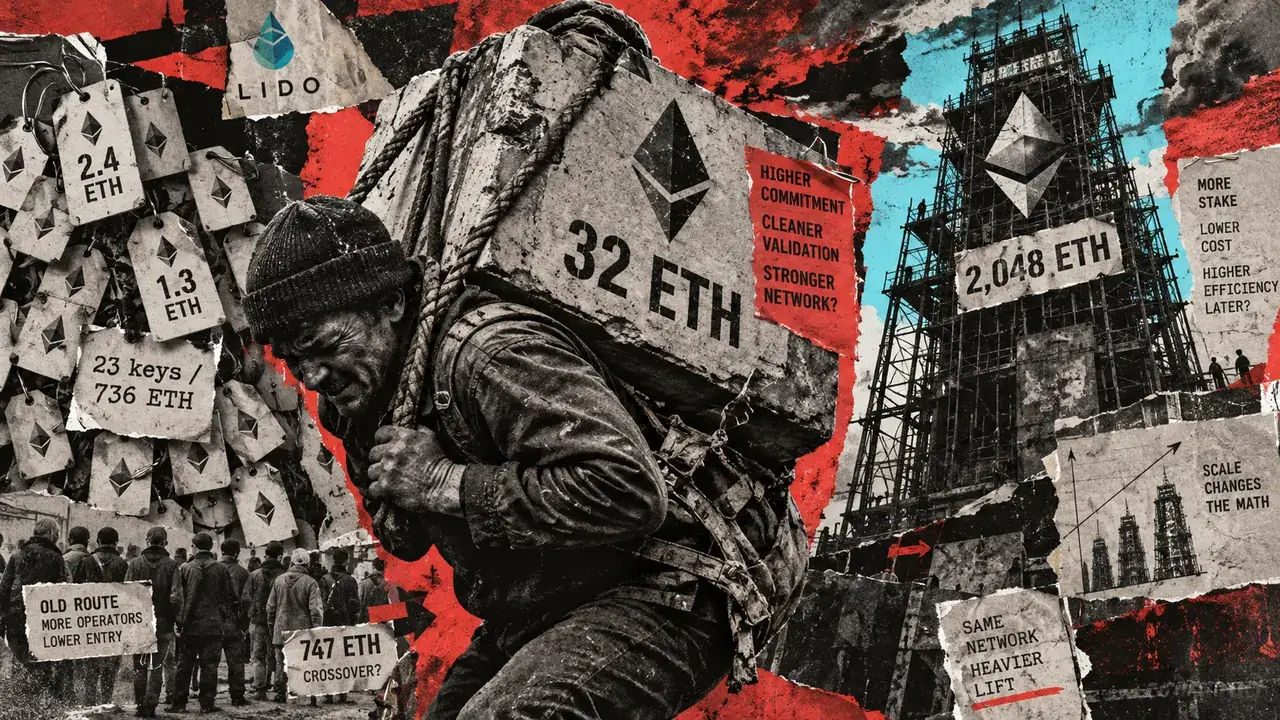
Lido’s proposed route for running larger Ethereum validators would require a 32 ETH entry bond, compared with 2.4 ETH for its existing default route. That higher collateral can become more efficient once enough stake is allocated to the validator, but an operator’s profile and place in the funding queue determine how useful the advantage is.
The October 1 deployment plan outlines Community Staking Module 0x02, a separate module for permissionless operators alongside the existing 0x01 route. It would support compounding validators with up to 2,048 ETH of effective stake, compared with 32 ETH for existing-route validators. Each validator is identified by a key.
The route remains on Hoodi testnet, with mainnet expected in Q4 2026. The deployment post describes preparations for mainnet and puts the module’s Staking Router parameters to a later vote. The July 20 approval of the launch proposal and September 1 testnet announcement were earlier milestones, rather than mainnet activation.
Measured as operator fees per ETH bonded, the new route reaches parity with a first existing default key near 747 ETH under equal yield and performance. But an operator spreading a 32 ETH budget across existing default keys raises that modeled threshold to about 1,330 ETH. These are fee-efficiency comparisons before costs, penalties and funding delays.
The proposed bond is 32 ETH for the first key and 30 ETH for each additional key. Under Lido’s existing 0x01 default profile, the amounts are 2.4 ETH and 1.3 ETH respectively.
The distinction between collateral and stake matters. The bond is the operator’s security deposit, held as stETH to cover losses and charges. The protocol supplies the validator’s stake separately. Posting a 32 ETH bond does not mean buying the validator’s delegated ETH or receiving a guaranteed allocation.
Ethereum’s EIP-7251 permits validators with 0x02 withdrawal credentials to compound, with a maximum effective balance of 2,048 ETH while retaining 32 ETH as the minimum activation balance. Lido’s bond curve follows the number of keys, so an existing 0x02 key would need no additional collateral as its stake grows.
At the maximum balance, the first key’s bond would equal 1.5625% of delegated stake, or 0.5 ETH of collateral per 32 ETH operated. The subsequent-key ratio would be about 1.465%. Those ratios describe a fully funded validator; a key operating with only its initial stake has a much larger collateral burden.
Operators would receive a 2% share of staking rewards, with 8% allocated to the treasury. The deployment setting giving operators 100% of the module fee means they receive that entire 2% slice. It is neither a 2% staking APR nor a claim on all validator rewards.
Why 747 ETH is only the first comparison
CryptoSlate’s calculations below hold gross staking yield, qualifying performance and operating duration equal. Existing-route portfolios are assumed fully funded and fee-eligible throughout the comparison period. They compare operator fees before infrastructure costs, gas, penalties and the bond’s own stETH returns.
If y is the gross staking yield over the comparison period and S is effective stake, proposed first-key fee income per ETH bonded is 0.02 × S × y ÷ 32. The existing first default key produces 0.035 × 32 × y ÷ 2.4. Equating them gives 746.67 ETH, or approximately 747 ETH.
The 747 ETH figure measures first-key fees per ETH of collateral, using different amounts of operator capital. It assumes both validators are funded and fee-eligible for the same period.
A 32 ETH budget can instead cover the bond for 23 existing default keys, using 31 ETH of bond and covering 736 ETH of delegated stake if all keys receive funding. One proposed-route key matches that portfolio’s total operator fees at 1,288 ETH. It matches fees per ETH actually bonded at about 1,330 ETH, because the existing portfolio posts only 31 ETH.
Verified profiles change the result again. Lido’s operator economics table gives Independent Community Stakers, or ICS, a 1.5 ETH first bond and 1.3 ETH thereafter, with a 6% reward share for their first 16 keys and 3.5% after. Verified independent clusters using distributed validator technology, or IDVTC, have a 1.5 ETH first bond and 0.5 ETH thereafter, earning 3.5% for their first 64 keys and 2% after. These profiles require eligibility; the proposed module has one permissionless profile.
| Existing-route profile | Keys and bond within a 32 ETH budget | Fully funded existing stake | New first-key stake for equal fees per ETH bonded |
|---|---|---|---|
| Default | 23 keys; 31 ETH | 736 ETH | About 1,330 ETH |
| Verified ICS | 24 keys; 31.4 ETH | 768 ETH | About 2,022 ETH |
| Verified IDVTC cluster | 62 keys; 32 ETH | 1,984 ETH | 3,472 ETH, above the 2,048 ETH ceiling |
The table divides fees by required bond actually posted. Default and ICS portfolios leave 1 ETH and 0.6 ETH unspent. Divide both alternatives by the same 32 ETH budget instead, and their total-fee crossovers are 1,288 ETH and 1,984 ETH respectively. Returns on spare capital are outside this fee-only model.
The ICS portfolio therefore leaves little room below the proposed validator ceiling for a fee-efficiency advantage. The modeled DVT cluster stays ahead throughout the available balance range. Neither result establishes net profitability, because the operational setups can have different costs.
Additional keys also need their own comparison. At the margin, a proposed 30 ETH bond versus an existing default 1.3 ETH bond gives a theoretical fee-efficiency crossover around 1,292 ETH, rather than the first-key 747 ETH figure.
Funding and penalties determine the net result
The October plan specifies a 16-position top-up queue. A key first receives its initial 32 ETH through the deposit queue, then enters a separate first-in, first-out queue for further funding.
Under Lido’s queue mechanics, top-ups serve the head in multiples of 2 ETH, limited by available stake. A partly filled key remains at the head until its remaining capacity is filled. Later keys cannot move ahead for top-ups, and a full queue throttles new initial deposits.
The proposed module cap is 2% of Lido stake. That constrains module allocation; it does not promise any operator a full validator.
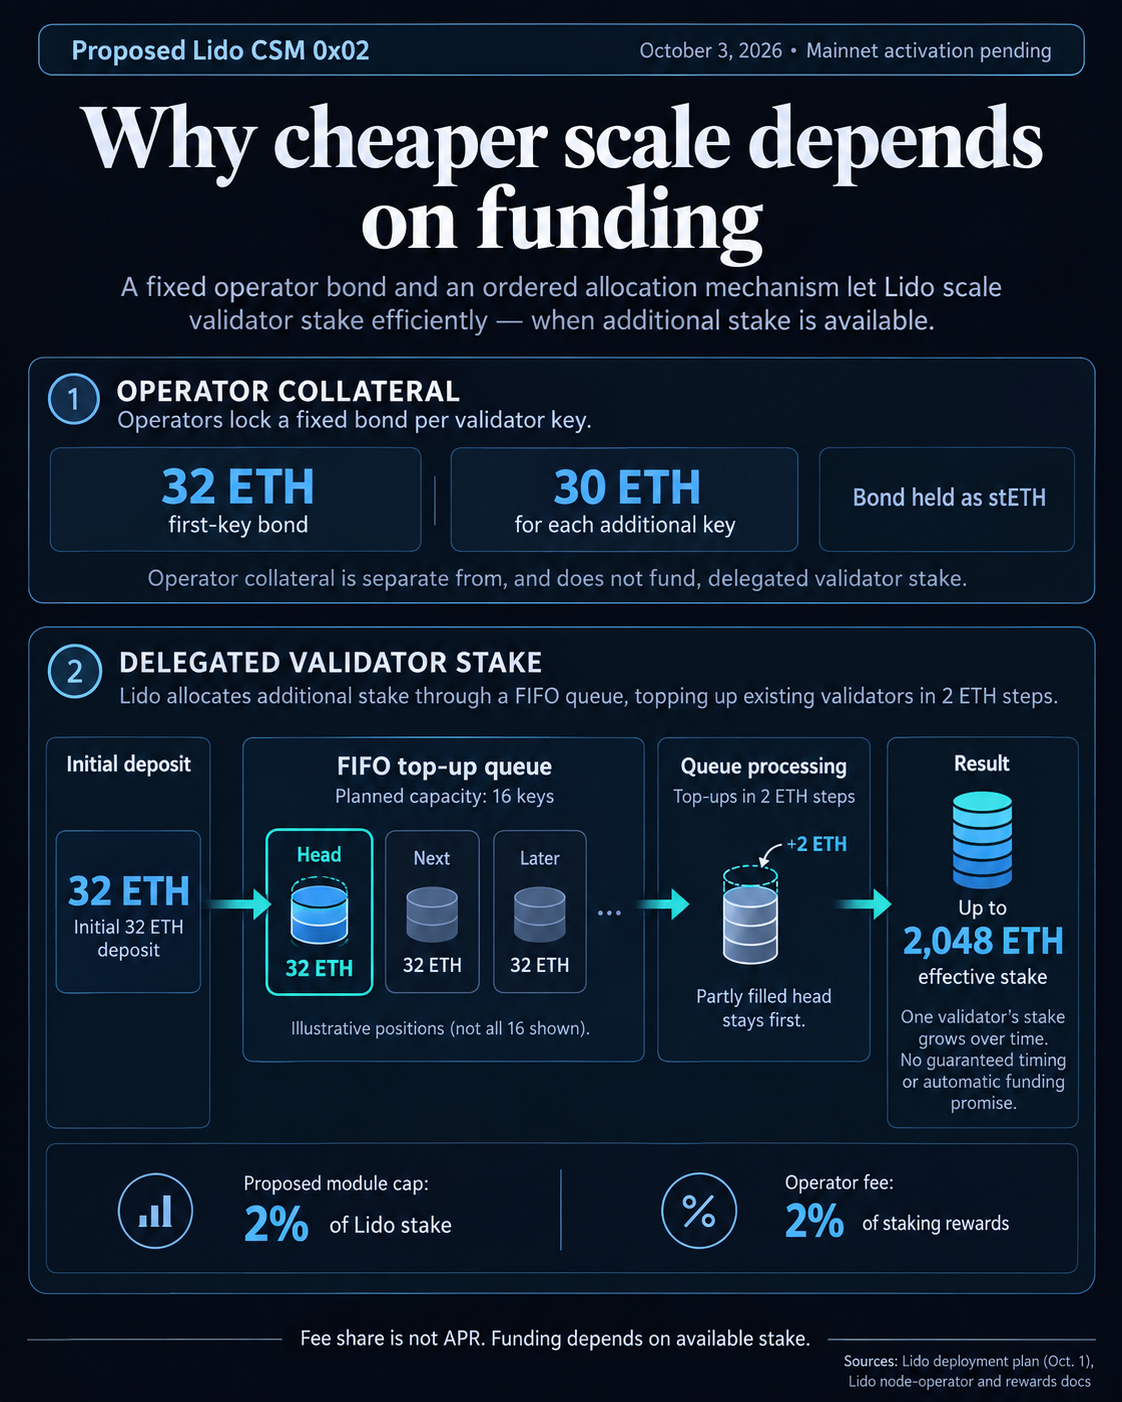
These rules turn a balance comparison into a timing question. An operator that eventually reaches 2,048 ETH may spend much of the comparison period waiting or running a smaller balance. The relevant figure is average reward-eligible effective stake over that period. Existing-route keys also need funding and activation, so the table’s fully funded portfolios are conditional benchmarks.
Compounding can help balances grow, but the module proposal itself makes capital efficiency dependent on current effective balance, module capacity and protocol inflows. A maximum-balance calculation cannot establish how quickly an operator will reach it.
Lido’s reward rules separate operator fees from the stETH rebase earned on collateral. Adding bond returns changes the total-income comparison. Comparing returns per ETH bonded requires the same bond-return rate and period before that stream can cancel out between alternatives.
Performance also affects payment. A validator below the threshold earns no operator rewards for that frame, while its bond can continue rebasing. Missing collateral must be restored before rewards are claimable.
The proposed configuration uses a 28-day frame, 3% performance leeway and a three-strike threshold with a six-frame strike lifetime. Balance-scaled penalties reach 16.512 ETH for bad-performance ejection and 6.4 ETH for delayed exit at a full 2,048 ETH balance. The exit-delay charge follows a four-day deadline and is settled after withdrawal.
A net comparison must add bond returns and subtract infrastructure, gas and assessed penalties, using actual funded time and reward eligibility. Fewer keys may change operating costs, but the parameters alone cannot price that difference.
Ahead of mainnet activation and the module-specific router vote, the useful signals are the final fee and cap settings, available funding and progress through the queue. The proposed route offers default operators a conditional path to better fee efficiency at scale; verified operators have stronger existing alternatives, and the lower-bond 0x01 route continues alongside it.