
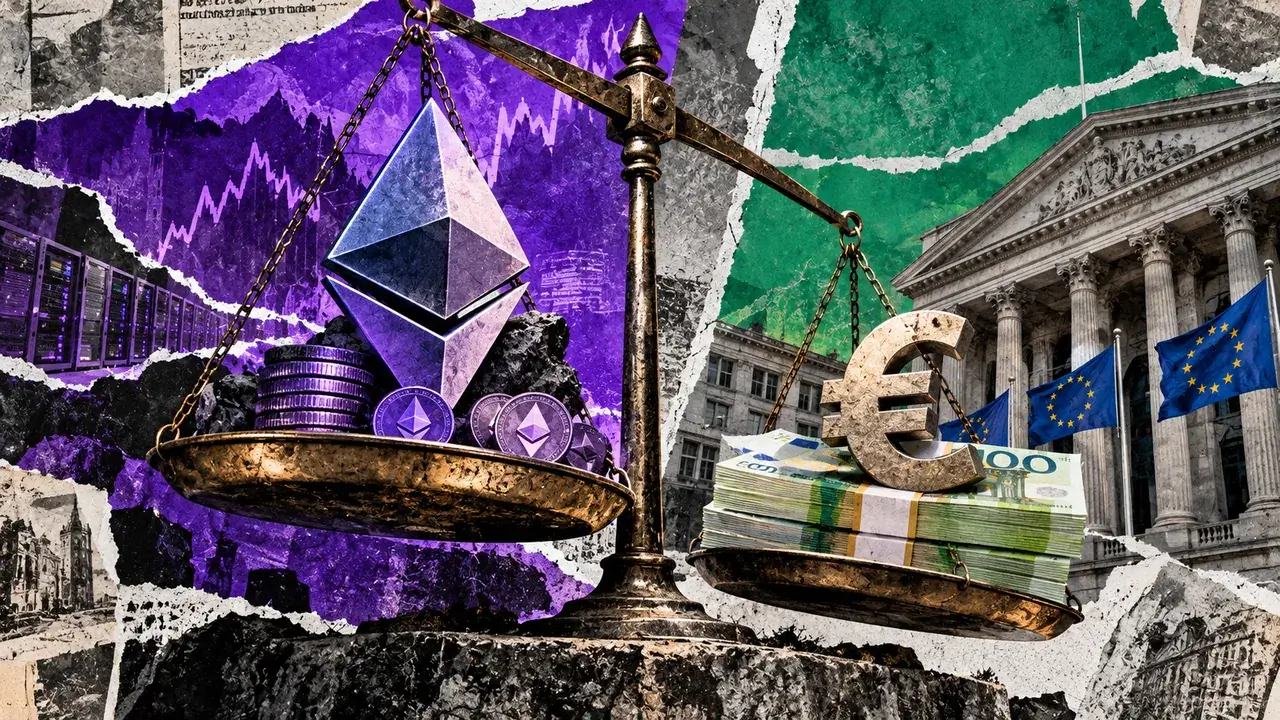
Put €10,000 into Ethereum staking at a 2.2% annual return and, if ETH’s price stays unchanged, you’ll earn about €220 over a year.
That’s just €7 more than the same amount would earn at the average rate on new euro household deposits with maturities up to one year, but with Ethereum’s price volatility attached to every cent of your investment.
Investors are still lining up, though, with roughly 1.38 million ETH waiting to enter staking as of Oct. 23 and an estimated wait of 24 days and nine hours.
Another 44.1 million ETH, more than 36% of the supply, is already staked to help secure the network and earn rewards. The queue is smaller than the 2.06 million ETH backlog tracked in August, but still leaves new direct validators waiting weeks to earn.
The mismatch makes more sense once you separate someone shopping for an interest rate from someone who has already decided to own ETH. BitMine has about $12 billion staked, and its decision involves earning extra tokens on a vast Ethereum position it intends to hold.
The €7 advantage comes with ETH attached
Staking commits ETH to Ethereum’s validation process, where operators run software that checks transactions and helps keep the network in agreement about its records.
Investors can run that operation themselves or use a service such as Lido, which pools ETH and issues stETH, a transferable token representing a share of the pool and its rewards.
In fact, staking has grown so much in scale and popularity that it’s moving beyond crypto-native platforms, with Interactive Brokers adding Ethereum staking for eligible clients in October. That means staking rewards now sit in the same account as cash and stocks.
Lido’s roughly 2.2% annual figure describes ETH rewards, so your token balance can increase while the euros you could get for it fall. Buying ETH to collect that income also exposes you to its price volatility, which can wipe out a year’s rewards long before you’ve a chance to enjoy them.
The tempting comparison is with the ECB’s 2.5% deposit facility, although that rate is only available to eligible banks placing money with the Eurosystem. In the ECB’s August data, ordinary savers received an average of 0.29% on overnight balances, while newly agreed household deposits of up to one year paid 2.13%.
Staking beats both averages before ETH’s price moves, while €STR, the wholesale euro overnight benchmark, was 2.442% on Oct. 22.
| €10,000 at a constant annual rate | Rate | 30 days | 90 days | One year |
|---|---|---|---|---|
| stETH, with unchanged ETH/euro price | 2.20% | €18.08 | €54.25 | €220.00 |
| €STR wholesale benchmark | 2.442% | €20.07 | €60.21 | €244.20 |
| Household deposits, agreed maturity up to one year | 2.13% | €17.51 | €52.52 | €213.00 |
| Household overnight deposits | 0.29% | €2.38 | €7.15 | €29.00 |
Illustrative simple accrual using a common 365-day year, with no compounding, taxes, or transaction costs; rates are held constant, and a term deposit needn’t allow withdrawal at 30 or 90 days. Lido’s quoted user rate already includes its standard rewards fee.
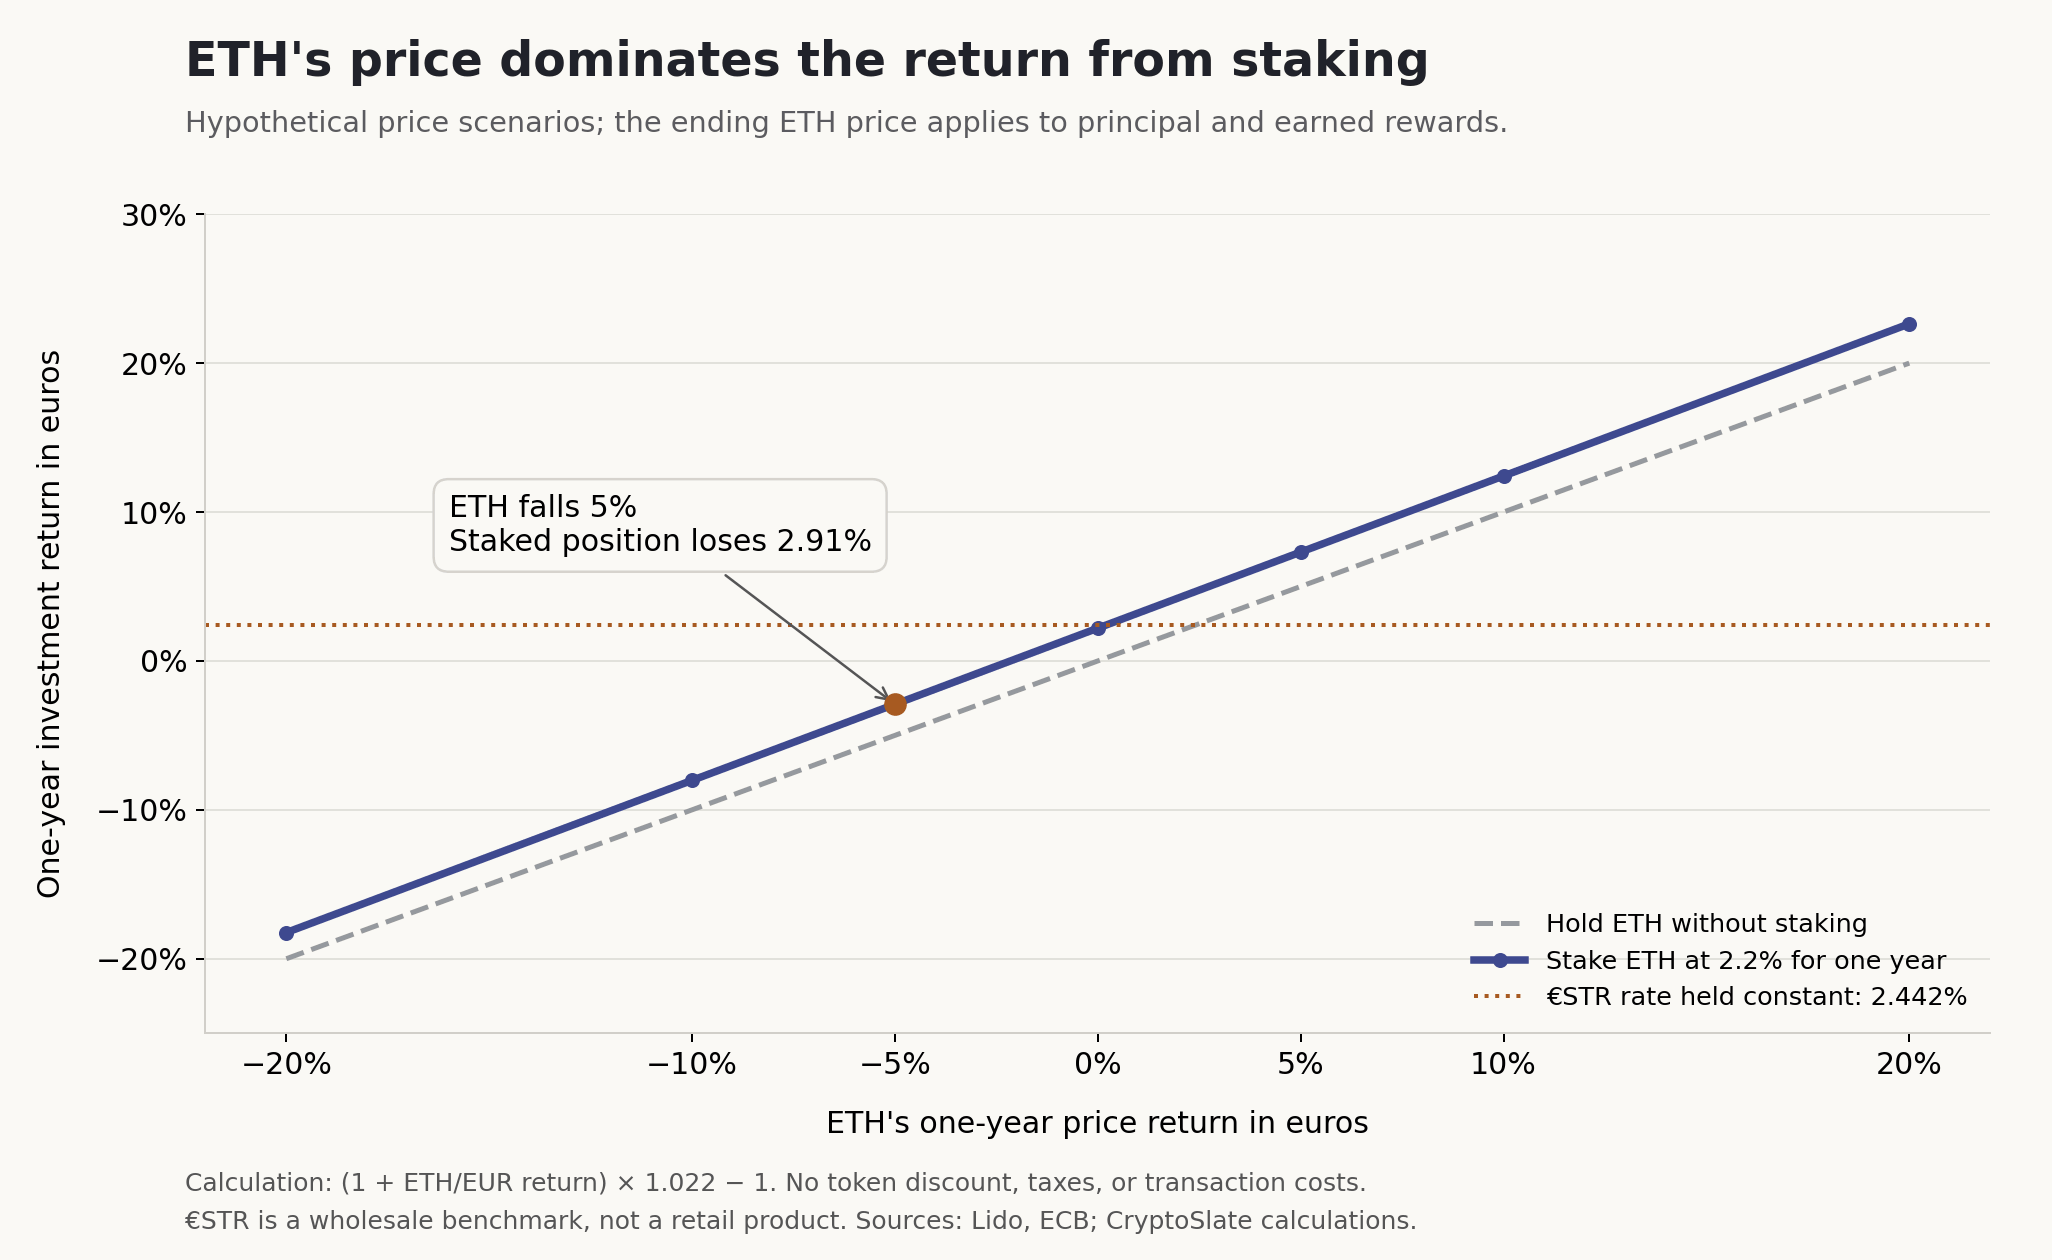
The annual gap between stETH and the €STR benchmark is €24.20 on that €10,000, whereas a 5% fall in ETH’s euro price would leave the staked investment worth about €9,709. You would own more ETH and still be down €291, because the lower price applies to both the rewards and the original investment.
What happens to €10,000: A year earning 2.2% more ETH, combined with a 5% fall in its euro price, gives €10,000 × 1.022 × 0.95 = €9,709. If ETH instead gains 5%, the result is €10,731, compared with €10,500 from holding the same starting ETH without staking.
Recent market prices show the same imbalance over shorter periods: ETH lost 9.08% in euros over the 30 days ending Oct. 22, while wrapped stETH lost 8.93%. Over the 90-day window, both gained roughly a third, with the staking token finishing only slightly further up.
| Historical euro market-price return | ETH | Wrapped stETH | Difference |
|---|---|---|---|
| September 22–October 22, 2026 | −9.08% | −8.93% | +0.15 percentage points |
| July 24–October 22, 2026 | +33.37% | +33.70% | +0.33 percentage points |
Calculated from CoinGecko snapshots at 00:00 UTC, excluding trading costs; the difference includes accrued staking rewards and movements in the token’s market premium or discount, rather than measuring protocol rewards alone.
Wrapped stETH keeps the number of tokens in your wallet fixed while each token represents an accumulating amount of stETH, letting its price capture rewards that ordinary stETH distributes through a larger balance.
Even then, the market can value the token above or below its underlying claim, adding another source of variation to what a seller receives.
The $12 billion Ethereum bet that explains staking demand
BitMine reported 5,067,309 ETH staked as of Oct. 18, worth about $12 billion at the $2,365 ETH price used in its announcement. It owned roughly 6.04 million ETH altogether, so collecting rewards meant putting an existing holding to work while keeping the exposure it had chosen.
The company reported a seven-day annualized staking yield of 2.58%, giving it an annualized revenue estimate of about $309 million on that stake. Its return differs from Lido’s, and the dollar estimate depends on ETH’s price and the assumed reward rate.
That income will help BitMine reach its goal of owning 5% of Ethereum’s supply, letting its holdings grow through rewards rather than additional purchases.
Fabian Dori, Sygnum’s chief investment officer, told CryptoSlate that “the marginal staker is no longer necessarily there for the return.”
He added that holders are staking because they want long-term exposure to Ethereum, even as lower income makes it harder for treasury companies to sell shareholders on ETH as a productive asset.
Someone who already wants to own the tokens can accumulate more through staking, provided the extra income justifies the costs and restrictions involved.
Moving into euros for a higher interest rate would also sell the ETH exposure they wanted to keep, making that a much larger investment decision than choosing between two quoted yields.
BitMine’s stake alone equals roughly 11.5% of the network’s rounded 44.1 million staked ETH, although ownership doesn’t establish independent control over the same share of validators.
Ethereum’s reward formula reduces the percentage return as more stake joins, because total rewards grow more slowly than the amount of ETH earning them. Individual stakers can earn lower rates while the network attracts more capital and validators continue doing their jobs properly.
Transaction tips and income from arranging transactions inside blocks, called maximal extractable value (MEV), add another variable to those rewards. Dori attributed part of the thinner yield to lower transaction fees, while the service used and its operators’ performance help determine what the holder receives.
Lido calculates its displayed rate from a seven-day moving average, with its standard 10% fee on rewards already deducted from the user return. The roughly 2.2% shouldn’t have another 10% taken off it, although trading costs and taxes can still reduce what an investor keeps.
The bill comes when you need the money
New direct validators earn no native staking rewards while waiting to activate, so the queue creates an income cost before the software starts working.
At the snapshot’s 2.46% network rate, a 32 ETH position waiting 24 days and nine hours would miss roughly 0.053 ETH in hypothetical rewards compared with being active immediately, assuming that rate stayed constant.
Lido spreads that wait differently, because new stETH holders can receive a share of rewards from validators already working while their incoming ETH is still pending.
More capital shares the existing earnings until the new deposits become productive, reducing the return per unit across the pool without automatically cutting anyone’s principal.
Exiting is a different process, with Ethereum’s exit queue separate from the entry wait and a liquid-staking token offering two routes back to ETH. Holders can request redemption through the protocol or sell to another trader, depending on whether waiting or accepting the available price costs them less.
Lido warns that withdrawals can face queues and market sales can suffer discounts, wider spreads, or worse execution when liquidity is scarce. Validators going offline can lose income, certain violations can trigger slashing that cuts the stake, and pooled services introduce dependencies on their contracts and operators.
We’ve seen those delays mount up, with a 43-day exit wait in September 2025 as Kiln withdrew validators during the SwissBorg-related security incident.
More recently, an October security incident involving MetaMask-operated validators sent hundreds of thousands of ETH toward the exit, showing how operational concerns can quickly affect withdrawal capacity.
Institutions may intend to hold ETH for years but still need access sooner, especially if obligations elsewhere on their balance sheets require cash.
Dori said that “at these levels, operational quality is the real differentiator, not the yield,” pointing to custody, slashing controls, and exit access.
He also warned that thinner income could encourage holders to borrow against their positions or restake them, committing assets to additional services that bring additional obligations and potential losses.
The ECB’s September increase to 2.5% gives conventional euro rates more pull, while Ethereum’s rewards depend on participation and activity rather than a decision to keep pace with a central bank.
Chasing the difference through more complex crypto strategies means accepting another risk on top of the ETH price already driving most of the investment’s return.
The distinction is visible in listed investment products, too. BlackRock’s non-staking Ethereum ETF still held far more assets and trading volume than its newer staking fund in September, suggesting that additional income is not the only factor shaping investor demand.
Someone with euros needs a reason to own ETH that survives a price fall much larger than the income earned, whereas someone already holding ETH can compare staking with leaving the same tokens unstaked.
The queue can keep attracting that second investor even when a savings-rate comparison looks unflattering, because the decision to own Ethereum has already been made and staking determines what the holding earns along the way.